
What PEP screening is about
PEP screening is the check of whether a client relationship involves a politically exposed person (PEP). Portfolio managers are financial intermediaries under Art. 2(2)(abis) AMLA, and PEP status can raise the risk classification of a relationship and, with it, the depth of the clarifications and the level of approval.
This article explains the screening process: whom to screen, when, against which sources, how to resolve hits and what to document. The full set of due diligence duties is covered in the guide to AMLA due diligence for portfolio managers, the legal framework in the AMLA knowledge hub. Sanctions screening follows its own rules: see sanctions and embargoes for Swiss asset managers.
Who counts as a PEP under Swiss AMLA
Art. 2a AMLA defines politically exposed persons by their function, not by name:
| Category | Who is covered | Risk classification |
|---|---|---|
| Foreign PEPs | persons who are or have been entrusted with prominent public functions by a foreign country, such as heads of state or government, senior politicians, senior government, judicial, military or party officials at national level, and senior executives of state-owned corporations of national significance | always a higher risk (Art. 6(3) AMLA) |
| Domestic PEPs | persons who are or have been entrusted with prominent public functions at national level in Switzerland in politics, government, the armed forces or the judiciary, and senior executives of state-owned corporations of national significance | higher risk in combination with one or more further risk criteria (Art. 6(4) AMLA) |
| PEPs in international organisations | persons who are or have been entrusted with a prominent function by an intergovernmental organisation or an international sports federation, such as secretaries general, directors, deputy directors and board members | higher risk in combination with further risk criteria (Art. 6(4) AMLA) |
| Family members and close associates | persons closely connected to a PEP through family or for social or professional reasons (Art. 2a(2) AMLA) | classified like the PEP they are connected to (Art. 6(3) and (4) AMLA) |
International sports federations are the International Olympic Committee and the non-governmental organisations it recognises that regulate one or more official sports at global level (Art. 2a(5) AMLA). The FINMA Anti-Money Laundering Ordinance repeats this classification in Art. 13(3) and (4) AMLO-FINMA.
When PEP status ends
Domestic PEPs are no longer regarded as politically exposed once 18 months have elapsed since they relinquished their position; the general due diligence duties remain (Art. 2a(4) AMLA). The Act sets no such period for foreign PEPs or PEPs in international organisations, whose definition covers persons who «are or have been» entrusted with the function.
Whom to screen in a client relationship
PEP status counts in every role. The PEP rules of Art. 13(3) and (4) AMLO-FINMA apply regardless of whether the persons involved act as contracting party, controlling person, beneficial owner of the assets or person with power of attorney (Art. 13(5) AMLO-FINMA). The screening therefore covers:
- the contracting party;
- the controlling person of an operating legal entity;
- the beneficial owner of the assets;
- every person with power of attorney over the relationship.
The reference for later matching is the identification data collected when the relationship is taken up: for a natural person as contracting party, name, first name, date of birth, residential address and nationality (Art. 44(1) AMLO-FINMA).
When to screen: onboarding, ongoing monitoring and trigger events
- At onboarding: before the relationship is taken up, because the risk classification determines who approves it.
- During the relationship: the financial intermediary ensures effective monitoring of business relationships and transactions so that higher risks are identified (Art. 20(1) AMLO-FINMA); a client can take up a public function after onboarding.
- On trigger events: a new beneficial owner, controlling person or holder of a power of attorney, a change in the client's professional activity, or information that the client holds a public function.
As soon as higher risks become apparent, the additional clarifications are initiated without delay and completed as quickly as possible (Art. 17 AMLO-FINMA). AMLA sets no fixed screening interval: the regularity of checks is determined by the risk represented by the customer (Art. 6(1) AMLA), and the required records are checked periodically and updated, with periodicity, scope and type based on the customer's risk (Art. 7(1bis) AMLA).
PEP screening lists and sources
Neither AMLA nor AMLO-FINMA names a specific PEP list or database. For additional clarifications, the ordinance mentions, depending on the circumstances, written or oral information from the contracting party, the controlling person or the beneficial owner, visits at their place of business, the consultation of generally accessible public sources and databases and, where appropriate, enquiries with trustworthy persons (Art. 16(1) AMLO-FINMA). The results are checked for plausibility and documented (Art. 16(2) AMLO-FINMA).
A practical source mix combines three elements:
- Client information: a question on current and past public functions in the onboarding documents, for every person in the relationship.
- PEP database: functions, family members and close associates, checked against the identification data.
- Public sources: official websites, registers and media to verify a function and its dates.
The internal directives set out the business policy on politically exposed persons and the criteria for higher-risk relationships (Art. 26(2) AMLO-FINMA); they are also the place to record the sources and the matching rules.
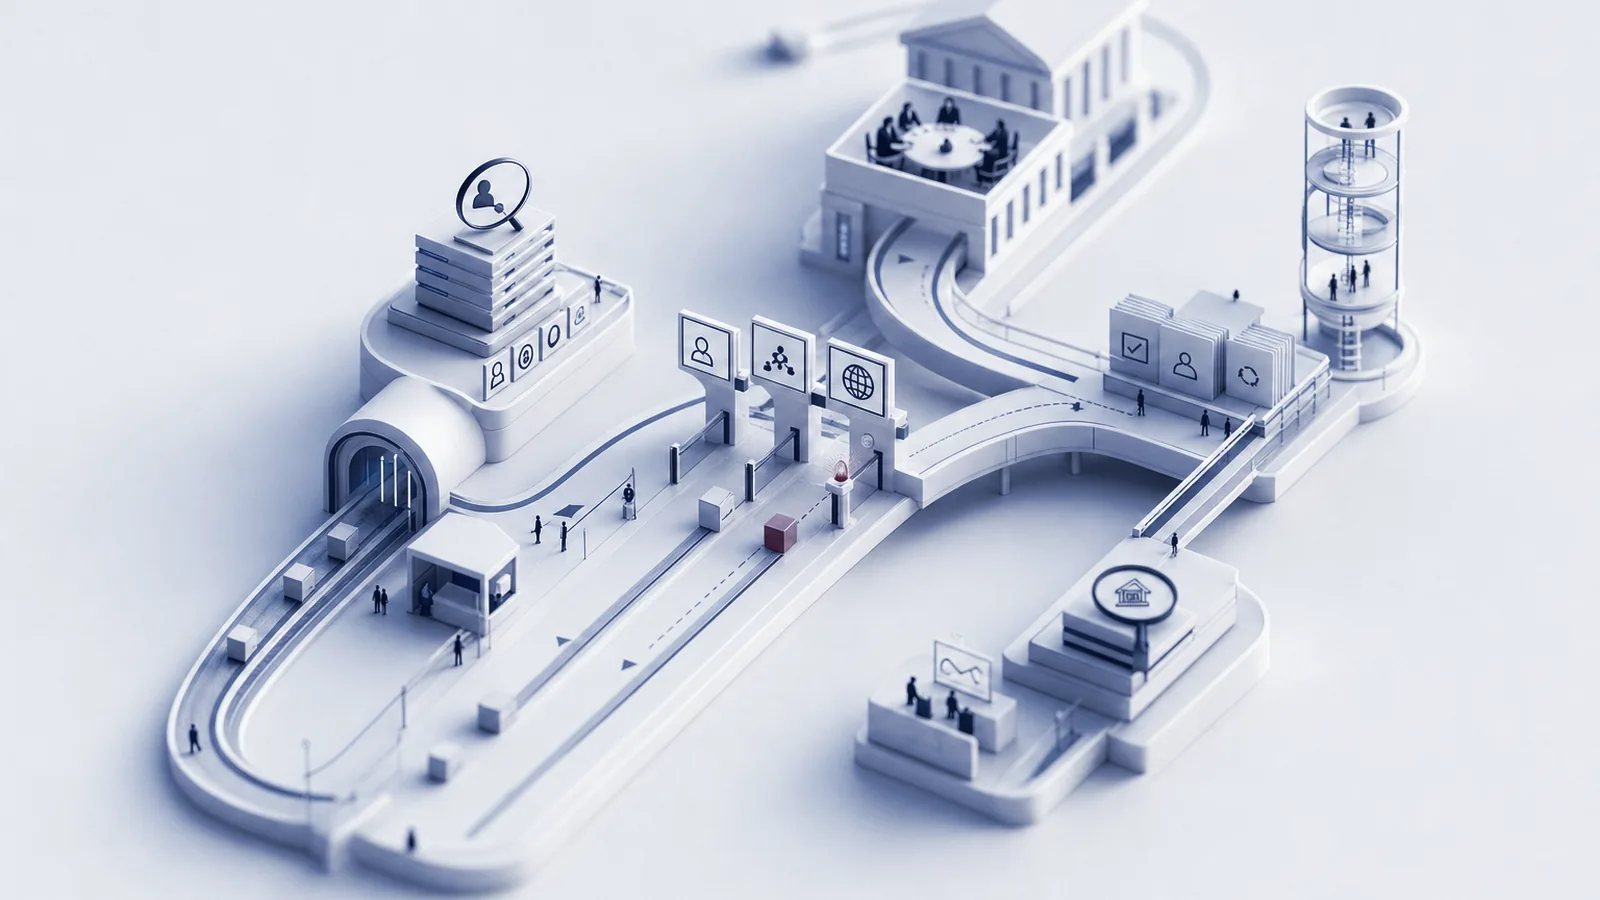
PEP screening process: hits, false positives and escalation
- 1Collect the datanames and identification data of the contracting party, the controlling person, the beneficial owner and every person with power of attorney.
- 2Run the checkagainst the sources defined in the internal directives; record date, source and result.
- 3Review potential matchescompare date of birth, nationality, residence and function with the identification data. A name match alone does not establish PEP status.
- 4Close false positivesrecord why the hit does not concern the client and which data were compared.
- 5Classify confirmed hitsforeign PEP, domestic PEP, PEP in an international organisation, or family member or close associate; for domestic PEPs and PEPs in international organisations, check whether further risk criteria apply. The financial intermediary identifies and flags higher-risk relationships internally (Art. 13(6) AMLO-FINMA).
- 6Escalatein the cases defined in the internal directives, the AML unit is consulted and the highest management body informed (Art. 26(2)(d) AMLO-FINMA).
- ✓Resulta documented classification, the additional clarifications started and the approval prepared at the right level.
Enhanced due diligence and senior management approval
For higher-risk business relationships, the financial intermediary clarifies the economic background and the purpose of the relationship (Art. 6(2)(c) AMLA) and carries out additional clarifications with reasonable effort (Art. 15 AMLO-FINMA). Depending on the circumstances, these cover in particular whether the contracting party is the beneficial owner of the assets brought in, the origin of those assets, the origin of the wealth of the contracting party and of the beneficial owner, their professional or business activity, the background and plausibility of larger incoming payments, the purpose of withdrawn assets, and whether a PEP is involved.
The level of approval follows the classification:
| PEP relationship | Approval of the relationship | Continuation |
|---|---|---|
| Foreign PEP, family member or close associate | highest management body or at least one of its members (Art. 19(1)(a) AMLO-FINMA) | decision every year (Art. 19(1)(a) AMLO-FINMA) |
| Domestic PEP or PEP in an intergovernmental organisation, family member or close associate, with further risk criteria | highest management body or at least one of its members | decision every year |
| PEP in an international sports federation, family member or close associate, with further risk criteria | a superior person, a superior unit or the management (Art. 18 AMLO-FINMA) | regular checks of all higher-risk relationships (Art. 19(1)(b) AMLO-FINMA) |
| Domestic PEP or PEP in an international organisation without further risk criteria | level determined by the risk represented by the customer (Art. 6(1) AMLA) | ongoing monitoring |
The highest management body also orders regular checks of all higher-risk relationships and their monitoring and evaluation (Art. 19(1)(b) AMLO-FINMA). How PEP relationships feed into the firm's own risk analysis is covered in the article on FINMA Supervisory Notice 04/2026 on the AML risk analysis.
Documentation and periodic review
Records of the clarifications are kept so that specially qualified persons can reliably assess the business relationships and compliance with the Act (Art. 7(1) AMLA). For portfolio managers, AMLO-FINMA specifically lists, among the documents to be kept, a written note on the results of applying the higher-risk criteria and a written note or records on the results of the additional clarifications (Art. 74(1)(c) and (d) AMLO-FINMA). The documentation is organised so that FINMA, the audit firm or the supervisory organisation, among others, can form a reliable judgement on compliance with the anti-money laundering duties within a reasonable time (Art. 22(1) AMLO-FINMA).
A complete PEP file holds the screening results with date and source (closed false positives included), the PEP category and risk classification, the clarifications on the origin of assets and wealth, the approval with date and decision-maker, the yearly continuation decisions and, for domestic PEPs, the date they left office.
PEP screening checklist
- All roles screened: contracting party, controlling person, beneficial owner, persons with power of attorney
- Sources and matching rules recorded in the internal directives
- Screening completed before the relationship is taken up; trigger events defined
- Every potential match resolved and documented
- PEP category and further risk criteria assessed; relationship flagged internally
- Origin of assets and wealth clarified; approval obtained at the required level
- Yearly continuation decisions and the 18-month period for domestic PEPs tracked
How Peak Compliance supports portfolio managers
Under its responsibility, a financial intermediary may designate qualified external persons as its AML unit if its size or organisation does not allow an own unit or one would be disproportionate (Art. 25(4) AMLO-FINMA). Peak Compliance supports portfolio managers in setting up and running PEP screening through its AML advisory: internal directives and source selection, the review of hits and the preparation of approval decisions. Contact us via the contact page.