
On 8 October 2026, the Swiss Financial Market Supervisory Authority (FINMA) published the partial revision of its circular. The amendments reflect technological developments and increasing risks associated with manipulated identity documents, artificial intelligence and deepfake technologies.
What Is Changing?
The key changes at a glance:
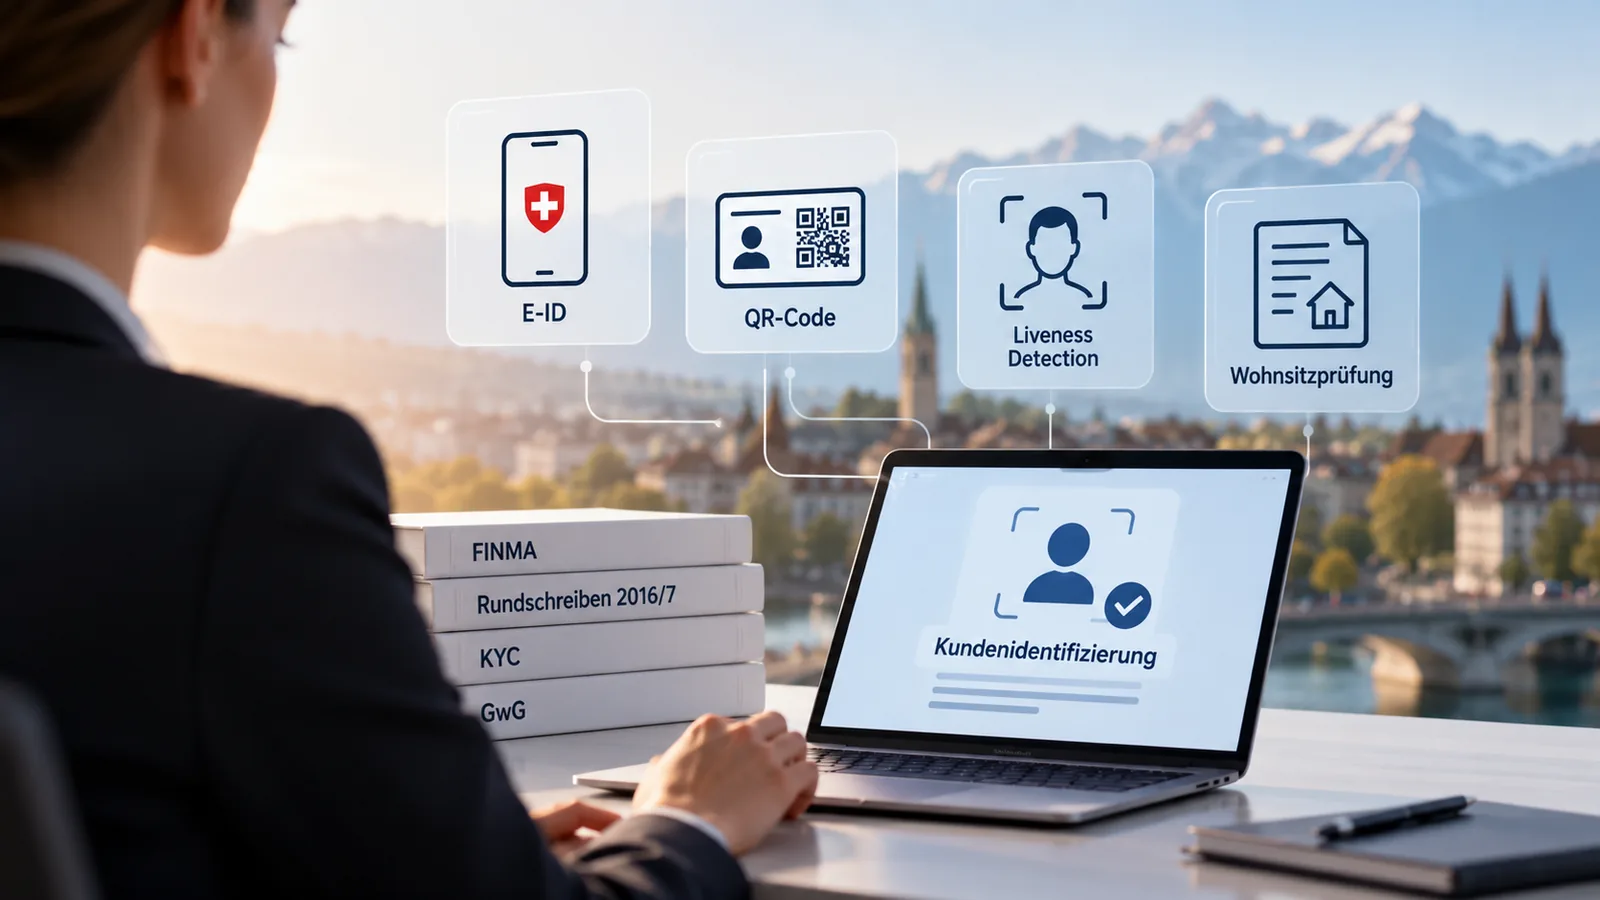
- Swiss electronic identity (E-ID): FINMA is establishing the regulatory framework for the future use of the Swiss E-ID as an alternative to physical identification documents. The introduction of the E-ID is expected in 2027.
- QR codes: Official identity documents containing a QR code, such as the Swiss driving licence, will be recognised as equivalent to documents with a machine-readable zone (MRZ).
- Liveness detection: Identification using the E-ID and certain procedures involving a qualified electronic signature (QES) will require technical measures to verify that the identification request genuinely originates from the contracting party.
- Digital residential address verification: Additional digital procedures will be permitted, provided they reliably establish the contracting party's residential address.
- Electronic signatures: Certain identification procedures using a QES will be subject to additional residential address verification requirements.
What Are the Implications for Portfolio Managers and Managers of Collective Assets?
Portfolio managers under Art. 17 FinIA and managers of collective assets under Art. 24 FinIA remain independently responsible for complying with their anti-money laundering (AML) due diligence obligations. These include the proper identification of the contracting party when establishing a business relationship.
The revised circular provides additional options for conducting client identification digitally. Such procedures may simplify onboarding and reduce administrative work, particularly for firms with an international client base.
From a practical perspective, firms should consider the following questions:
- Which digital identification procedures are currently used during client onboarding?
- Do these procedures meet the applicable requirements for security, identity verification and documentation?
- Are internal KYC processes and policies aligned with the identification procedures used?
- Are risks relating to manipulated identification documents and AI-generated content adequately addressed?
The new identification options do not alter the remaining AML due diligence obligations. In particular, the requirements concerning identification of beneficial owners, client risk classification, additional due diligence and ongoing monitoring remain applicable.
Conclusion
The partial revision of FINMA Circular 2016/7 provides greater flexibility for digital client identification while addressing emerging fraud risks.
Portfolio managers and managers of collective assets are not generally required to introduce new identification technologies. However, firms already using digital identification procedures, or planning to implement them, should assess whether their processes meet the applicable regulatory requirements.
Peak Compliance AG specialises in compliance and risk management outsourcing solutions for portfolio managers and managers of collective assets in Switzerland and Liechtenstein.