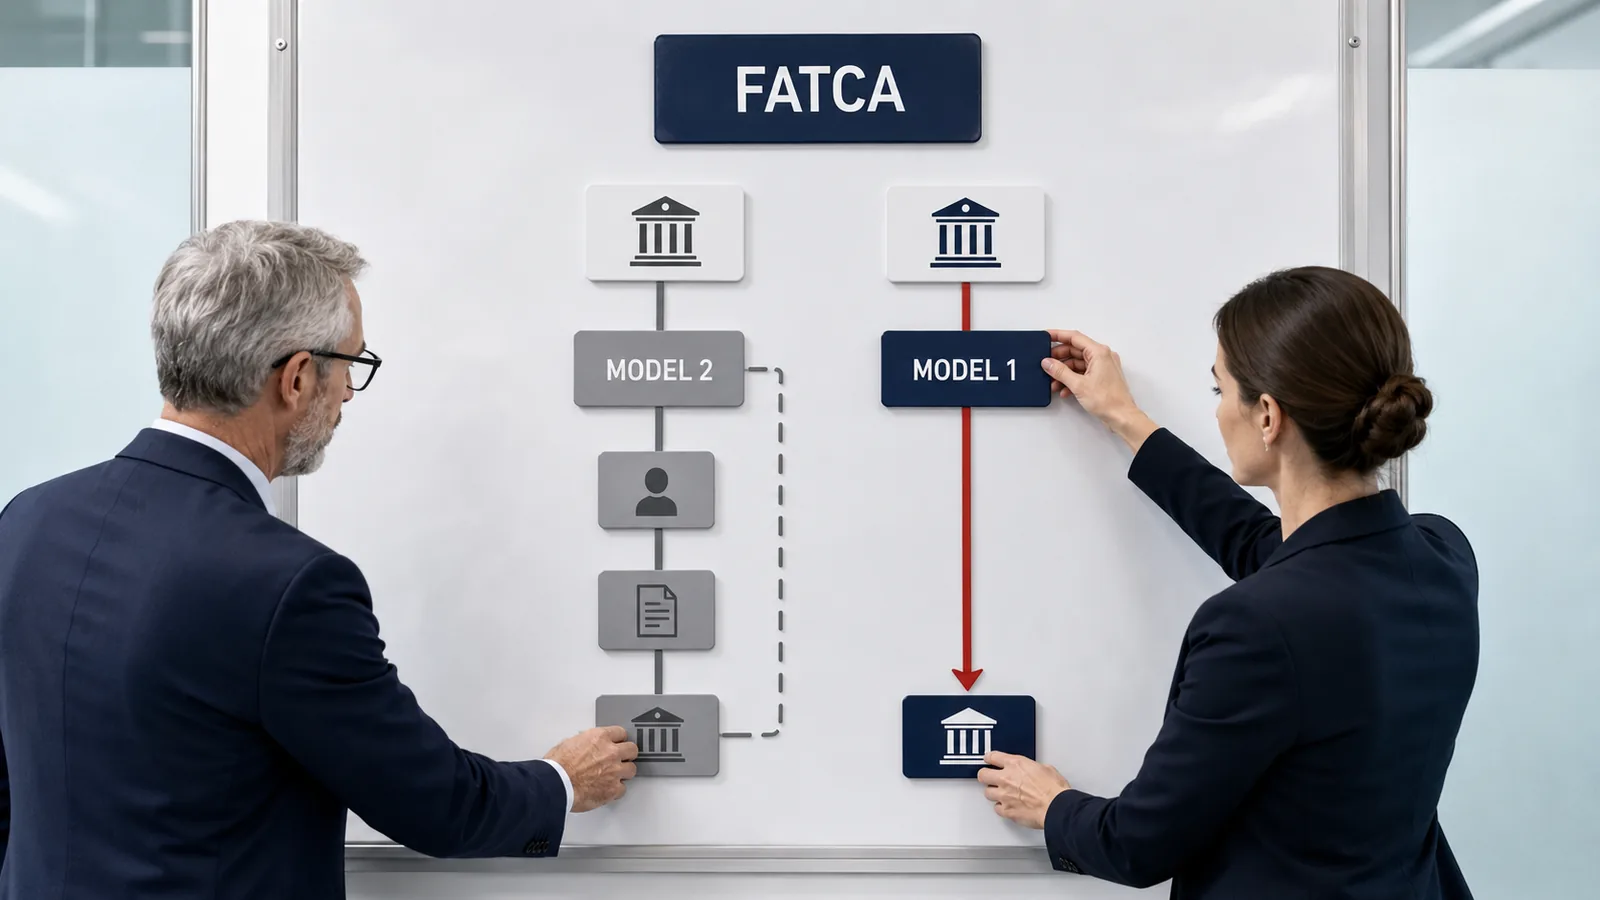

On 27 June 2024, Switzerland and the United States signed a new FATCA agreement. With the planned transition from the current Model 2 to Model 1, expected to take effect on 1 January 2027, Swiss financial institutions will face several adjustments. In this article, we focus specifically on the consequences for asset managers under Art. 17 FINIG and managers of collective assets under Art. 24 FINIG.
Previous Practice under Model 2
Under the previous Model 2 framework, Swiss asset managers were considered financial institutions under FATCA, but they had no direct reporting obligation as long as client custody accounts were held with banks. They could, however, voluntarily register with the IRS and obtain the status of “registered deemed compliant” with a GIIN number. Many chose this route to demonstrate FATCA compliance more clearly to banks. Without registration, a self-certification using Form W-8BEN-E was sufficient.
Managers of collective assets also fell within the FATCA definition. Their classification, however, depended on Annex II of the FATCA Agreement. If they were treated as reporting financial institutions – for example, fund managers directly dealing with US investors or maintaining accounts – they were required to register with the IRS and obtain a GIIN. If they qualified as non-reporting financial institutions, for instance where they acted solely through custodian banks, they had no direct reporting obligation.
Changes from 2027 under Model 1
With the transition to Model 1, several changes will apply. Asset managers under Art. 17 FINIG will continue to be classified as non-reporting financial institutions and will still have no direct FATCA reporting obligation. However, the “registered deemed compliant” status will cease to exist. Those previously registered must deregister from the IRS by the end of 2026, thereby losing their GIIN. From 2027 onwards, only the “certified deemed compliant” status via self-certification using Form W-8BEN-E will remain.
For managers of collective assets under Art. 24 FINIG, the decisive factor remains whether they are classified as reporting or non-reporting financial institutions. Reporting managers will no longer report directly to the IRS, but instead to the Swiss Federal Tax Administration (ESTV), which will forward the data to the US. This eliminates the direct certification requirement vis-à-vis the IRS, reducing administrative burden. Non-reporting managers will maintain their existing status and continue to document it through Form W-8BEN-E.
Practical Implications
In practice, this means that asset managers must complete any necessary IRS deregistrations by the end of 2026 and fully align their processes with self-certification. Managers of collective assets should review their FATCA classification well in advance and, if reporting, adapt their reporting processes to the ESTV interface by 2027. Non-reporting institutions can continue with their existing procedures but should ensure proper documentation with banks and investors. Further reading: MiCAR and Switzerland: When Swiss Financial Intermediaries Are Affected.
Recommended Actions
- Status review: Assess whether and how an IRS registration currently exists.
- Plan deregistration: Registered institutions that will no longer qualify as reporting must deregister from the IRS.
- Clarify classification: Managers of collective assets must clearly establish whether they fall under “reporting” or “non-reporting” financial institutions.
- Prepare self-certification: Update Form W-8BEN-E and provide it to banks.
- Adapt processes: Reporting institutions must adjust reporting systems to the ESTV interface by 2027.
- Ensure communication: Inform banks, fund administrators, and investors in a timely manner.